PriceTracker GLP-1

The facts

Weight loss

Excluded

Type 2 diabetes

Not indicated

Prior auth

Required (MASH, cardiovascular)

Typical cost

Plan-specific

Who actually decides this

Not the logo on your card, most of the time. Three parties sit between you and the answer, and knowing which one is saying no tells you who to ask.

  1. 1

    The pharmacy benefit manager

    No single PBM to name here, which is itself the finding. Different plans under this name use different benefit managers, so one national statement about the formulary would be wrong.

  2. 2

    Your employer, if the plan comes through work

    Weight-loss drugs are usually a category an employer buys or declines, not something the insurer includes by default. That is why two people holding identical cards get opposite answers, and why the useful question for member services is whether your plan includes the weight-loss medication benefit at all, before anything about criteria.

Get your real answer

If you take Wegovy for weight only and are 21 or older, Medi-Cal Rx will not pay; the cash routes below are what is left. If you have MASH or established cardiovascular disease, ask your prescriber to submit the diagnosis code or a prior authorization request. If you received a Notice of Action denying coverage, Medi-Cal gives you the right to ask for a State Hearing.

Coverage is plan-specific: this page reports what Medi-Cal publishes, not a promise about your plan. Not medical or insurance advice.
What it actually costs you

If your plan covers it

The manufacturer savings card is the lever, and it is worth being precise about what it does: it takes up to $100 a month off your copay. It does not set your price to $25. You reach the advertised $25 only if your copay is roughly $125 or less, so on a $300 copay the card leaves you paying $200.

The Wegovy card, and what the cap does to your number →

If you are on Medicare, Medicaid or TRICARE For Life

The card is closed to you. Every manufacturer savings card in this category excludes government beneficiaries, and that is deliberate rather than an oversight you can argue around. The Medicare GLP-1 Bridge, at $50 a month, is the route worth asking about by name.

What Medicare covers, and what the Bridge does not count toward →

If the answer is no, or you have no plan

A copay card needs a copay to work on, so with no coverage it does nothing. That leaves the manufacturer’s own cash prices, the discount cards, and the compounded market, which is cheaper again and not FDA-approved. We priced all of them against each other.

Every route without insurance, priced →Whether GoodRx helps here →

All four manufacturers cap their cards differently. The caps compared side by side.

Common questions

Does Medi-Cal cover Wegovy for weight loss?

No. Wegovy is excluded from Medi-Cal's standard formulary for weight management, and only an employer buy-up or a formulary exception changes that.

Do I need prior authorization for Wegovy with Medi-Cal?

Required (MASH, cardiovascular). Your prescriber submits it with the documentation the policy asks for, which for weight-management requests usually means a BMI threshold and a period of documented lifestyle or behavioural change.

Can I use a Wegovy coupon with Medi-Cal?

If you have commercial insurance, the Wegovy savings card takes up to $100 a month off your copay rather than setting your price to $25, so you reach the advertised figure only if your copay is roughly $125 or less. If you are on Medicare, Medicaid or TRICARE For Life, every manufacturer card in this category excludes government beneficiaries and the card is closed to you.

What if Medi-Cal will not cover Wegovy?

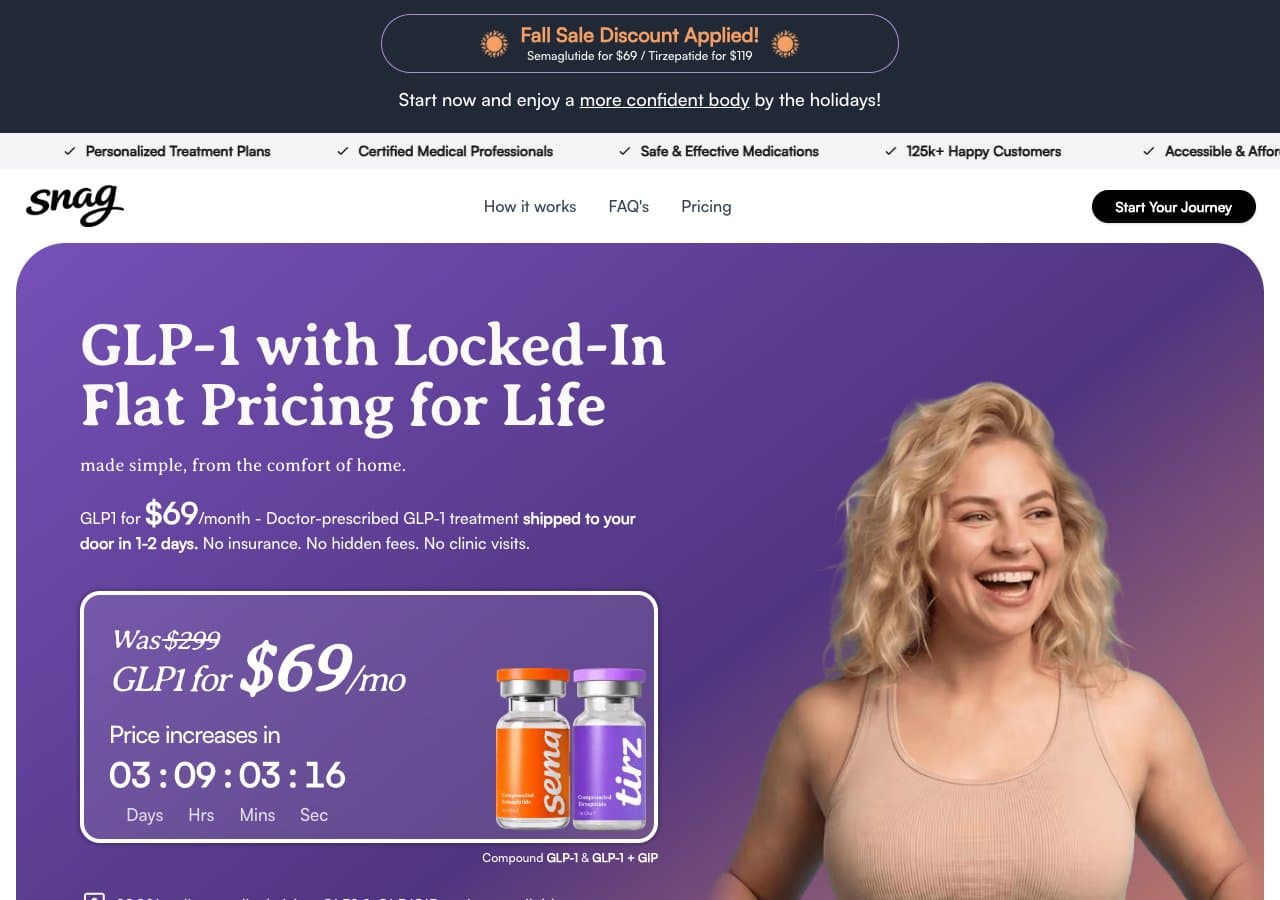
Cash-pay is the fallback and it is cheaper than most people expect. The cheapest verified semaglutide program we track is $69 a month at SnagRx, with no insurance involved. Compounded programs are not FDA-approved, which is the trade-off to weigh against the price.

Coverage changes. We watch it.

Formularies move every year, and so do prices. Check your own insurer, or get the weekly price email.

Check your insurer