PriceTracker GLP-1

The facts

Weight loss

Generally no

Type 2 diabetes

Yes, with step therapy

Prior auth

Step therapy required

Typical cost

Plan-specific

The criteria, as published

5 of 9 criteria are stated in the Molina Healthcare documents we read. Tap a row for the exact wording. Where a cell says not published, the documents we read do not say, and the line under it is how to find out.

Formulary status
Tier 3 with step therapy on the 2026 Utah formulary
“*Incretin Mimetic Agents (Glp-1 Receptor Agonists)*** OZEMPIC (0.25 OR 0.5 MG/DOSE) SUBCUTANEOUS SOLUTION PEN-INJECTOR 2 MG/3ML (Semaglutide) Tier 3 ST; QL (3 ML per 25 days)”
molinamarketplace.com · 2026-04-01
BMI threshold
Not published in what we readAsk member services for the written prior authorization criteria for Ozempic.
Qualifying conditions
Diabetes required for diabetes drugs (California 2026 Agreement)
“Weight loss drugs, unless approved by Medical Necessity for morbid obesity (Class III Obesity). Only individuals with diabetes are eligible to receive coverage of applicable drugs indicated for the treatment of diabetes.”
molinamarketplace.com · 2026 plan year
Lifestyle program
Not published in what we readAsk whether a diet, exercise or behavioral program has to be documented, and for how long.
Step therapy
Yes: step therapy required
“ST Step Therapy is required. If we have paid for you to have the required Step Therapy drug(s) in the past, this drug will be paid for at the pharmacy without need for a Prior Authorization or Step Therapy exception request.”
molinamarketplace.com · 2026-04-01
Quantity limit
3 mL per 25 days (0.25/0.5 mg and 1 mg pens)
“*Incretin Mimetic Agents (Glp-1 Receptor Agonists)*** OZEMPIC (0.25 OR 0.5 MG/DOSE) SUBCUTANEOUS SOLUTION PEN-INJECTOR 2 MG/3ML (Semaglutide) Tier 3 ST; QL (3 ML per 25 days)”
molinamarketplace.com · 2026-04-01
Renewal
Not published in what we readAsk how long an approval lasts and what the renewal needs.
Plan can exclude it?
Yes: weight loss drugs are listed as non-covered
“Weight loss drugs, unless approved by Medical Necessity for morbid obesity (Class III Obesity). Only individuals with diabetes are eligible to receive coverage of applicable drugs indicated for the treatment of diabetes.”
molinamarketplace.com · 2026 plan year
2026 change
Not published in what we readAsk whether Ozempic's status changed this year or changes at your next renewal.

Who actually decides this

Not the logo on your card, most of the time. Three parties sit between you and the answer, and knowing which one is saying no tells you who to ask.

  1. 1

    The pharmacy benefit manager · CVS Caremark

    Molina Healthcare hands its formulary to CVS Caremark, so what is preferred, excluded or subject to step therapy is CVS Caremark’s decision rather than Molina Healthcare’s. When you read that a formulary changed, this is the company that changed it.

  2. 2

    Your employer, if the plan comes through work

    Weight-loss drugs are usually a category an employer buys or declines, not something the insurer includes by default. That is why two people holding identical cards get opposite answers, and why the useful question for member services is whether your plan includes the weight-loss medication benefit at all, before anything about criteria.

  3. 3

    Your state or region

    These plans are sold state by state, each with its own drug list, so the answer for one state does not carry to the next. Check the formulary for your state and plan year.

How prior authorization works here

Six steps. Specifics come from the criteria above; where Molina Healthcare does not publish one, the step says what to ask for.

  1. 1

    Confirm the benefit exists

    Before any paperwork, ask whether your plan includes the weight-loss drug benefit. On whether a plan can leave it out, the documents say: Yes: weight loss drugs are listed as non-covered.

  2. 2

    Get the criteria in writing

    Ask for the written prior authorization criteria for Ozempic, so your prescriber answers the plan's questions rather than guessing at them.

  3. 3

    Your prescriber documents the clinical picture

    Current and baseline BMI, with dates. Conditions: Diabetes required for diabetes drugs (California 2026 Agreement). Records of any diet, exercise or behavioral program.

  4. 4

    Answer step therapy, if there is any

    What the documents say: Yes: step therapy required. If you already tried that drug, or cannot take it, the request should say so with dates.

  5. 5

    Submit, then track it

    Your prescriber sends the plan’s form with the notes. Write down the date and the reference number, and ask how you will hear back.

  6. 6

    Plan for the renewal

    Ask how long the approval lasts and what the renewal needs, so the gap does not catch you out.

Get your real answer

Ask your doctor which step drug Molina requires first, or have them file a step therapy exception if you already tried it. Molina's pharmacy claims run through CVS Caremark, so CVS Caremark can confirm formulary status and rejected claims.

Coverage is plan-specific: this page reports what Molina Healthcare publishes, not a promise about your plan. Not medical or insurance advice.
What it actually costs you

If your plan covers it

The manufacturer savings card is the lever, and it is worth being precise about what it does: it takes up to $100 a month off your copay. It does not set your price to $25. You reach the advertised $25 only if your copay is roughly $125 or less, so on a $300 copay the card leaves you paying $200.

The Ozempic card, and what the cap does to your number →

If you are on Medicare, Medicaid or TRICARE For Life

The card is closed to you. Every manufacturer savings card in this category excludes government beneficiaries, and that is deliberate rather than an oversight you can argue around. The Medicare GLP-1 Bridge, at $50 a month, is the route worth asking about by name.

What Medicare covers, and what the Bridge does not count toward →

If the answer is no, or you have no plan

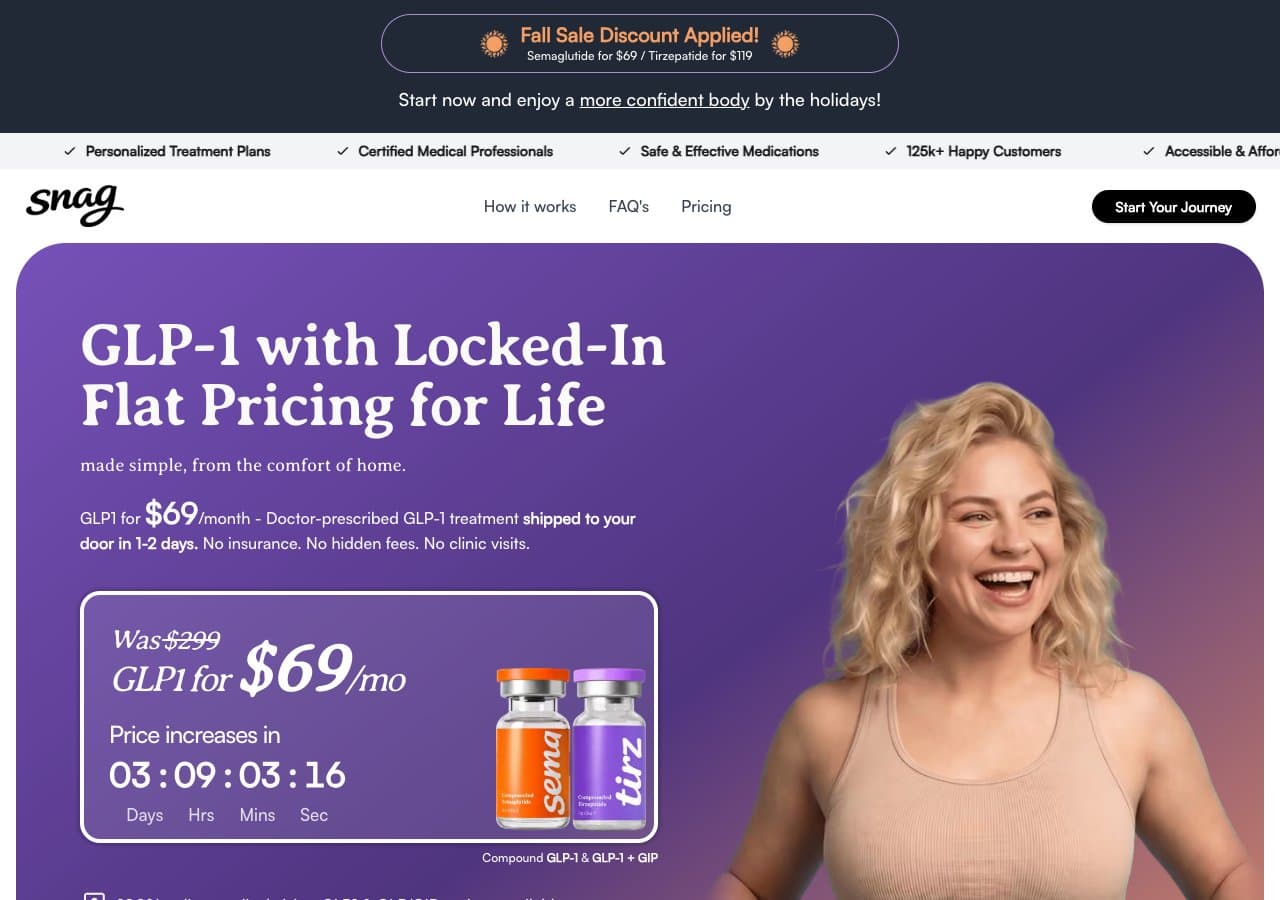
A copay card needs a copay to work on, so with no coverage it does nothing. That leaves the manufacturer’s own cash prices, the discount cards, and the compounded market, which is cheaper again and not FDA-approved. We priced all of them against each other.

Every route without insurance, priced →Whether GoodRx helps here →

All four manufacturers cap their cards differently. The caps compared side by side.

If Molina Healthcare says no

Read the denial letter for the reason first. Three different things get called a denial, and only two of them are worth appealing.

The plan excludes the category

Not a decision about you, so chart notes will not move it. The routes are a formulary exception, a different plan at open enrollment, or paying cash.

Step therapy

A sequence, not a refusal. Documented failure, intolerance or a reason you cannot take the first drug is the way through.

Criteria not met

The most winnable. It usually fails on missing paperwork, such as a BMI without a date or a lifestyle program with no records.

Which kind of no you got, and what each one needs →

Checklist · for the call

Questions to ask Molina Healthcare

Call the member services number on your card. Ask these in order, and write each answer down.

  1. Is Ozempic on my plan's formulary for weight management, and at what tier?
  2. Does my plan include the weight-loss medication benefit, or is that category excluded?
  3. Does Ozempic need prior authorization? Can you send me the written criteria?
  4. What BMI, and which conditions, does the policy require?
  5. Do I have to show a diet, exercise or behavioral program first? For how long?
  6. Do I have to try another drug first (step therapy)?
  7. Is there a quantity limit on each fill?
  8. How long does an approval last, and what does the renewal need?
  9. What will I pay each month at the pharmacy once it is approved?
  10. Which pharmacy do I have to use: retail, mail order or specialty?
  11. If it is denied, how do I appeal, and what is the deadline?

Write down: date of call · name of the person · reference number · what they said

The receipts

Every claim on this page traces to Molina Healthcare’s own published material or a primary document, quoted verbatim, with the date we read it.

Common questions

Does Molina Healthcare cover Ozempic for weight loss?

Generally not. Ozempic is not the brand Molina Healthcare covers for weight loss, and using it for weight is off-label.

Does Molina Healthcare cover Ozempic for type 2 diabetes?

Yes, with step therapy. Diabetes is the indication plans cover far more readily than weight management, so if you have a type 2 diagnosis the answer is usually yes with prior authorisation, even where weight-loss coverage is excluded.

Do I need prior authorization for Ozempic with Molina Healthcare?

Step therapy required. Your prescriber submits it with the documentation the policy asks for, which for weight-management requests usually means a BMI threshold and a period of documented lifestyle or behavioural change.

Can I use a Ozempic coupon with Molina Healthcare?

If you have commercial insurance, the Ozempic savings offer takes up to $100 a month off your copay rather than setting your price to $25, so you reach the advertised figure only if your copay is roughly $125 or less. If you are on Medicare, Medicaid or TRICARE For Life, every manufacturer card in this category excludes government beneficiaries and the card is closed to you.

Who decides whether Molina Healthcare covers Ozempic?

CVS Caremark owns the formulary, so what is preferred, excluded or subject to step therapy is decided there rather than by Molina Healthcare. Your employer separately decides whether the weight-loss drug category is included in your plan at all. Those two parties, not the name on your card, produce most of the variation people run into.

Why do I get a different answer from someone else with Molina Healthcare?

Because Molina Healthcare plans are sold state by state, each with its own drug list. Two members in different states, or on different plan levels, can get different answers.

What if Molina Healthcare will not cover Ozempic?

Cash-pay is the fallback and it is cheaper than most people expect. The cheapest verified semaglutide program we track is $69 a month at SnagRx, with no insurance involved. Compounded programs are not FDA-approved, which is the trade-off to weigh against the price.

Coverage changes. We watch it.

Formularies move every year, and so do prices. Check your own insurer, or get the weekly price email.

Check your insurer